Compare home loans in Las Vegas

Start with the upfront costs, total monthly payment and what you need to prepare. Compare your options before deciding which mortgage fits your home purchase.

Plan for the costs of buying a home

Separate your upfront costs

The down payment is only part of the cash you may need. Review closing costs, prepaid taxes and insurance, and any reserves the lender requires you to retain after closing. Ask which costs may be covered by eligible credits or assistance.

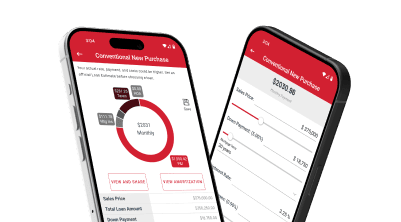
Compare the total payment

Compare principal and interest together with property taxes, insurance and any mortgage insurance. Consider the loan term, points, lender credits and closing costs alongside the interest rate.

Prepare for the next steps

The timeline depends on your application, documents, property review and any conditions. Ask what is needed now and what still requires verification; no closing date or approval is guaranteed.
See our rates

Understand the loan programs

These summaries explain different loan types, not a determination that you qualify. Ask which options are available for your property and circumstances.

Valley West Mortgage, NMLS #65506. Equal Housing Lender. Loan availability and terms are subject to credit approval and program guidelines. This is not a commitment to lend.

Bring your goals and questions to the conversation.
Contact us
FHA
FHA insures mortgages made by approved lenders; it does not make the loan or guarantee borrower approval. Borrowers pay mortgage insurance, so compare the upfront and ongoing costs as well as the other loan terms.
Conventional
A conventional mortgage is not insured or guaranteed by a government loan program. Conventional loans can be conforming or non-conforming; the requirements differ. Mortgage insurance may apply. Compare the loan terms and the credit, income, asset and property requirements.
VA
VA guarantees part of qualifying loans for eligible Veterans, service members and certain surviving spouses. A Certificate of Eligibility establishes eligibility for the benefit; the lender still reviews credit, income, the property and other requirements. It is not final loan approval.
USDA
The USDA Single Family Housing Guaranteed Loan Program supports approved-lender loans for eligible primary residences in eligible areas. Household income, the property address and repayment ability must be checked. The guarantee protects the lender; fees and closing costs still need to be considered.
Reverse Mortgage (HECM)
An FHA-insured Home Equity Conversion Mortgage (HECM) may help eligible older borrowers purchase a principal residence with a cash contribution and required counseling. Borrowers must occupy and maintain the home and pay property taxes and insurance. Not making monthly principal-and-interest payments does not remove those obligations; failing to meet the loan terms can make the loan due.
Non-QM
Non-QM describes loans that do not meet Qualified Mortgage criteria. Pricing, documentation and underwriting requirements can differ. For consumer mortgages covered by the federal ability-to-repay rule, lenders must still make a reasonable, good-faith repayment assessment. Availability depends on the loan and borrower.

Know what to prepare and what remains conditional

01
Discuss your purchase plans
Have the property state and ZIP code, expected purchase timing and intended occupancy ready. Discuss a comfortable payment range, the funds you can use and your main questions before choosing a loan.
02
Gather documents and apply
If you choose to apply, the lender will request information about income, assets, debts and the property. Ask which documents are needed for your circumstances. A preapproval is conditional and is not a commitment to fund a particular home purchase.
03
Compare your Loan Estimate
Compare the loan amount, rate, APR, repayment term, points, lender credits, total payment and cash to close. Ask about differences and whether the rate is locked. An estimate is not final loan approval.
04
Complete the required reviews
Underwriting and the property review may identify conditions or require more documents. Before signing, review the final loan terms and closing figures. Closing and funding depend on the remaining requirements and applicable timing rules.
Your purchase plans
Note where you plan to buy, when you hope to move and how you will use the property. Tell the lender if the home will be a primary residence, second home or investment property.
Buyer preparation checklist
Your funds and documents
Separate the down payment, closing costs and money needed after closing. Have recent income and asset information available, and ask how gifts, assistance or credits must be documented.
Buyer preparation checklist
Your comparison questions
Ask about the total monthly payment, cash to close, mortgage insurance and remaining approval conditions. Compare the same loan amount and term when reviewing different estimates.
Questions to bring

Talk through your home purchase with Valley West Mortgage.

Call (702) 696-9900
Continue with your rate quote

⏰ Your offer will be delivered to your inbox in less than a minute!