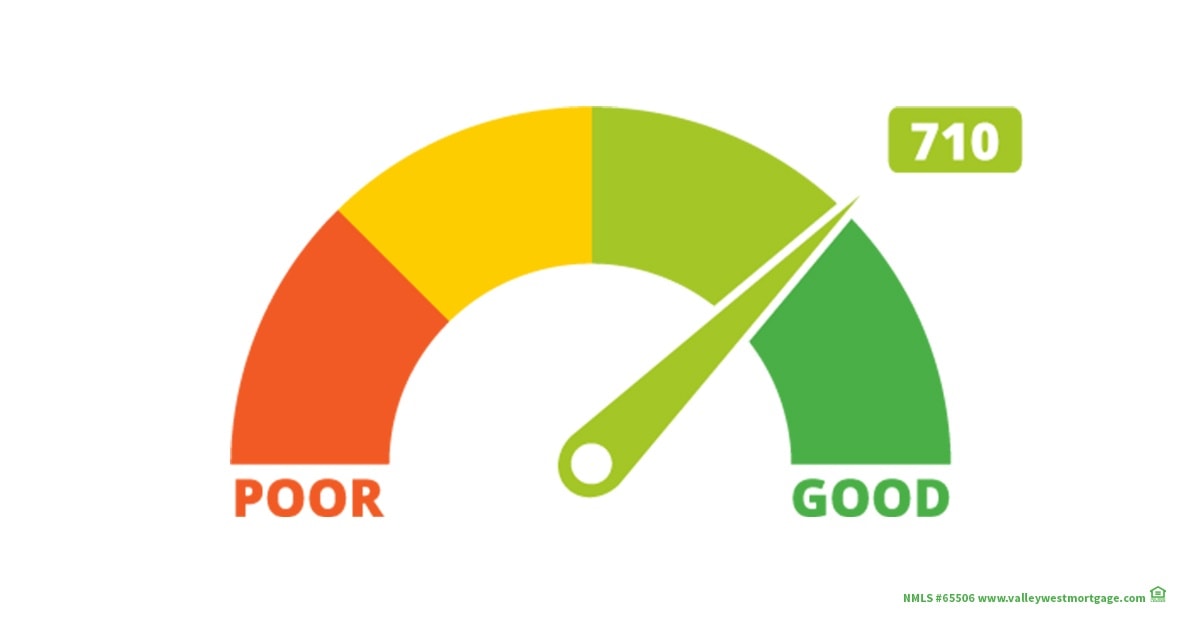
Quick answer (October 2026): It can be. FICO labels 670 to 739 as "Good," and a 710 is above HUD's published FHA score lines. VA does not set a minimum credit score. A score does not guarantee approval or a particular rate: the lender also reviews your income, debts, savings and the home.
One detail matters for conventional loans. On Fannie Mae's pricing chart dated September 30, 2026, a 710 sits in the 700 to 719 band. The next band starts at 720, just 10 points away. In one column of that chart, the gap is 0.125% of the loan amount. On a hypothetical $400,000 loan, that is $500. It is a charge Fannie Mae assesses lenders, not a fee or a saving we quote you. Whether any of it reaches your price depends on the lender and your loan.
Want to know your real mortgage score?
With your permission, a Las Vegas loan officer can review the credit report and score a lender would use, and tell you plainly whether anything is worth fixing first. Ask whether the pull is a hard or soft inquiry before you agree. No obligation to apply.
Get your fast quoteThe useful question is what a lender can offer with your full file. Your score is one input. Here is how to put a 710 score in context without treating a score range as a promise.
Key takeaways
- 710 is "Good" on FICO's scale (670 to 739). It is above HUD's published FHA score lines. VA and Fannie Mae's automated review set no minimum score. But a score is not an approval, and a lender's own rules can be stricter.
- Lenders use the middle of three scores. The CFPB says most mortgage lenders pull scores from Equifax, Experian and TransUnion and use the middle one. Your app score may not match it.
- 720 is the next pricing band. Fannie Mae prices conventional loans in 20-point bands. Moving from 700 to 719 into 720 to 739 can lower a pricing charge, depending on your loan.
- Check before you wait. Fix report errors first. Then ask whether a specific change could move you up a band before you delay a purchase.
Is a 710 credit score good enough for a mortgage?
It can be, subject to the loan program and the lender's review. A score alone cannot confirm whether your income supports the payment, your funds can be used or the property meets the loan rules. A good credit history also does not erase a recent missed payment or a debt that was left off the application.
The CFPB puts it plainly:
“Your credit score is only one component of your mortgage lender’s decision, but it’s an important one.”Consumer Financial Protection Bureau, “Does my credit score affect my ability to get a mortgage loan or the mortgage rate I pay?” consumerfinance.gov
The CFPB lists other factors, including your credit report, your debts, your savings, your assets and your income. That is why two people with a 710 can get different answers. One may have a steady paycheck and low debts. The other may have a large car payment that pushes their debt-to-income ratio, or DTI, too high. DTI is your monthly debt payments divided by your monthly income before taxes. Our debt-to-income guide shows the math.
Start with a mortgage preapproval review. Ask the lender what it has checked, which items remain open and whether the letter has conditions. That gives you a more useful answer than a general online score threshold.
Where does 710 sit on the scale?
FICO scores run from 300 to 850. FICO groups them into five ranges. A 710 sits in the middle of the "Good" range, 40 points above its bottom and 30 points below "Very good."
| FICO score | FICO's label | Where 710 fits |
|---|---|---|
| 800 to 850 | Exceptional | 90 points higher |
| 740 to 799 | Very good | 30 points higher |
| 670 to 739 | Good | 710 is here |
| 580 to 669 | Fair | 41 points lower |
| Below 580 | Poor | 131 points lower |
A credit-score range describes risk under a scoring model. It is not a mortgage approval scale. The score on a banking app may use a different model or report date from the score your mortgage lender obtains.
The CFPB explains how credit scores can affect mortgage eligibility and pricing. Compare the actual loan terms offered to you rather than assuming a label such as "good" fixes your rate.
What are the actual program minimums?
There is no single minimum that covers every mortgage. Rules differ by program, how the file is reviewed and the lender's own requirements. An overlay is a lender rule that can be stricter than the program's base rule.
| Loan type | Published score rule | What it means for a 710 |
|---|---|---|
| Conventional (Fannie Mae) | No minimum score for loans run through Desktop Underwriter. Manually reviewed loans have minimums in Fannie Mae's eligibility rules. | Score is not the limit. Pricing bands still apply (see below). |
| FHA | HUD's floor is 500. A score of 580 or higher is eligible for FHA's maximum financing. | Above both HUD lines. The lender may set its own minimum. |
| VA | VA does not set a minimum credit score. Lenders can set their own credit standards. | Ask the lender what it requires for your file. |
| Jumbo and non-QM | Set by each lender or investor. | Ask for the lender's written rule for your loan size. |
FHA loans are insured by the Federal Housing Administration and VA loans are guaranteed by the Department of Veterans Affairs. FHA loans and VA-guaranteed loans are made by private lenders. Neither the FHA nor the VA endorses any particular lender.
For example, Fannie Mae's current credit-score guidance says its Desktop Underwriter loan casefiles do not require a minimum credit score. Desktop Underwriter, or DU, is its automated risk review. Manual reviews have separate requirements. This does not mean all scores qualify or that a lender must approve a file.
Ask which program and review method apply to your application. Do not use an old universal "620 for conventional" statement as a current approval test. Government-backed programs have their own rules, and a lender still needs to review the rest of your file. If you are weighing programs, our FHA vs. conventional comparison and the FHA credit score guide go deeper.
Which credit score do mortgage lenders use?
Most mortgage lenders pull a report that combines all three credit bureaus. The CFPB says most lenders look at scores from Equifax, Experian and TransUnion and use the middle score for deciding what rate to offer you. So if your three scores are 698, 710 and 731, the lender would usually use 710.
Ask the lender which scoring model, credit reports and borrower score it used. Fannie Mae's current pricing chart lists either a Classic FICO score or a VantageScore 4.0, for lenders approved to use it. Do not assume either will match a free score displayed by a credit-card app.
For a joint application, ask how both borrowers' credit affects the review and price. Avoid averaging two app scores yourself. If a report contains an error, ask how to document and resolve it before relying on a revised score. Our guide to how FICO scores work explains the five factors behind the number.
Which pricing band is your score in?
Enter one score, or all three bureau scores if you have them. The checker finds the middle score, shows FICO's label for it and the band it falls in on Fannie Mae's conventional pricing chart. It does not show prices or approve anything.
Bands are from Fannie Mae's Loan-Level Price Adjustment Matrix dated September 30, 2026. Scores you enter stay in your browser. This checker is for learning only. It is not a quote, a credit decision or an approval, and the score a lender uses may differ.
Why can a credit-score band affect pricing?
Some loan pricing uses ranges of scores alongside other factors. For loans sold to Fannie Mae, Fannie Mae charges lenders a fee called a loan-level price adjustment, or LLPA, on many conventional loans. The fee depends on your score band, your loan-to-value and other loan features, and some loans qualify for waivers. A lender may pass it on to you through the rate or the points it offers. Moving into another band may change an adjustment, but it does not guarantee a lower final rate.
| Score band | LLPA in this column | On $400,000 (illustrative) |
|---|---|---|
| 740 to 759 | 0.875% | $3,500 |
| 720 to 739 | 1.250% | $5,000 |
| 700 to 719 (710 is here) | 1.375% | $5,500 |
| 680 to 699 | 1.750% | $7,000 |
In this one column, moving from 710 to 720 lowers the adjustment by 0.125%, or $500 on a hypothetical $400,000 loan. Moving down to 699 raises it by 0.375%, or $1,500. This is an illustration of how the chart works, not an estimate of what you would pay or save. Other columns show different gaps, and some show none. That is why a lender has to price your actual loan before anyone can say whether 10 points matter.
A Loan Estimate is a standard form showing proposed loan terms and costs. Use it to compare real offers. Ask whether each rate is locked and whether the offers use the same loan amount, term and closing date. Our rate lock guide explains what a lock covers.
Close to 720?
Ask a Valley West loan officer to price your loan at your current score. If a band change would matter for your file, we will say so, and if it would not, we will say that too. No obligation.
Get your fast quoteWhat about 714, 730, 738 or 790?
No one can price those scores in isolation. A small score change may have no effect in one scenario and matter in another. A higher score does not remove the need to meet income, funds and property rules.
On the Fannie Mae chart, 714 is in the same band as 710. A 730 or 738 is in the 720 to 739 band. A 790 is in the top band, 780 and above. Use the checker above to see where any score lands.
Ask the lender to identify a useful target, if there is one, for your actual loan. Have it explain what would change and what would remain uncertain. Do not delay a purchase based only on a generic score chart or a promised credit-repair result.
How does loan-to-value change the comparison?
Loan-to-value, or LTV, compares the loan amount with the property's value used for lending. It helps explain why two borrowers with the same credit score can receive different offers. Their down payments, property values or loan terms may differ.
Compare both the cash needed now and the full monthly cost. Keeping some savings after closing may matter to your household budget. Ask how a different down payment would affect your actual options before moving money. Pricing chart columns describe a loan's size against the home's value. They are not a down-payment requirement or an offer. Our how much house can I afford guide walks through the monthly budget.
Is it worth raising a 710 before you apply?
First, check whether your credit report is accurate. Then ask the lender whether a specific credit change could affect the programs or terms available to you. Separate a known reporting error from a general hope of improving the score.
FICO says the amount of debt you use against your credit limits makes up about 30% of a FICO score, and payment history about 35%. Those are the two largest factors FICO describes. Paying card balances down and paying on time fall inside them. Neither is a promise, and how much a score moves depends on your whole report.
- Confirm the mortgage score the lender is using.
- Ask which open conditions matter most in your file.
- Compare the cost of waiting with the possible benefit, without assuming that benefit will occur.
- Keep enough cash for the purchase and your own reserve needs.
If a report error is fixed, ask the lender about a rapid rescore. That is a request, made through the lender's credit company, to update your scores after a correction is documented. It is not credit repair, and it cannot remove accurate information. A lender decides whether a rescore is appropriate.
A lender can discuss a scenario; it cannot promise a future score or future rate. Read the four Cs of mortgage qualification to see how credit fits with the rest of the review.
What should you avoid changing during the mortgage process?
Before opening credit, financing a car, changing jobs or moving large sums, discuss the change with your loan team. Keep paying existing accounts on time. Retain records showing where funds came from and where they went.
Tell the lender promptly if something changes. An earlier preapproval does not make later changes irrelevant. See what underwriters check for the documents that help explain your file.
Frequently asked questions
Does a 710 credit score guarantee mortgage approval?
No. The lender must also review income, debts, funds, the property and the loan program's rules.
Is 710 a good credit score to buy a house?
Yes, by FICO's own label: 670 to 739 is "Good." It is above the published minimum scores for FHA loans, and VA does not set a minimum credit score. Approval still depends on your income, debts, savings and the home.
Will my mortgage score match the score in my banking app?
Not necessarily. The scoring model, credit report and report date can differ. The CFPB says most mortgage lenders use the middle of your three bureau scores. Ask the lender which score it used.
Is 710 good enough for an FHA or VA loan?
A 710 is above HUD's published FHA lines of 500 and 580. VA does not set a minimum credit score, but lenders can set their own credit standards. A lender can have a stricter rule and must review the rest of your file.
How far is 710 from the next pricing band?
10 points. On Fannie Mae's conventional pricing chart dated September 30, 2026, 710 is in the 700 to 719 band and the next band starts at 720. Whether that changes your price depends on your loan.
Should I wait for a higher score before applying?
Ask for a review of your actual file first. A higher score may help, but the benefit and timing are not guaranteed.
Does checking my own credit score lower it?
No. FICO says soft inquiries, such as viewing your own credit report, will not affect your FICO scores. A lender's credit pull for a mortgage application is a hard inquiry, which may affect your score.
Does shopping several mortgage lenders hurt a 710 score?
Not much if you shop in a short window. FICO groups mortgage inquiries made within 14 to 45 days, depending on the score version, into a single inquiry. Getting all your quotes within 14 days keeps it to one inquiry under any version.
What should you do next?
Use your score to start a conversation, not to declare yourself approved or ineligible. By FICO's label, a 710 is a "Good" score. Ask a lender to pull the score it will use, explain the full file and the remaining conditions, and show the written loan costs. If you are close to 720, ask whether the next band would matter for your loan. Then choose the next step that fits your budget and timing.
Find out what your actual mortgage score is
With your permission, a Valley West loan officer can review the three-bureau report lenders use, explain whether you sit near a band edge, and tell you plainly whether there is anything worth fixing first. Ask whether the pull is a hard or soft inquiry first. Valley West Mortgage is an independent mortgage lender in Las Vegas.
Get a fast quoteTalk to a Valley West specialist
Sources
Links open third-party sites we do not control.
- Consumer Financial Protection Bureau, Does my credit score affect my ability to get a mortgage loan or the mortgage rate I pay? (most lenders use the middle of three bureau scores; credit score is one component of the decision): consumerfinance.gov
- myFICO, What is a FICO Score? (score ranges and labels; payment history about 35%, amount of debt about 30%): myfico.com
- Fannie Mae, Loan-Level Price Adjustment Matrix, dated September 30, 2026 (score bands; Classic FICO or VantageScore 4.0; purchase LLPAs by score and LTV): singlefamily.fanniemae.com
- Fannie Mae Selling Guide B3-5.1-01, General Requirements for Credit Scores (no minimum score for DU loan casefiles): selling-guide.fanniemae.com
- HUD Single Family Housing Policy Handbook 4000.1 (FHA minimum decision credit scores of 500 and 580): hud.gov
- U.S. Department of Veterans Affairs, 2023 Loan Guaranty Conference, Credit Underwriting (no minimum credit score required): benefits.va.gov, and VA purchase loans (borrowers must meet VA's and the lender's credit standards): va.gov
- myFICO, Credit Checks: What are credit inquiries and how do they affect your FICO Score? (soft inquiries; 14-to-45-day mortgage shopping window): myfico.com
Updated October 18, 2026: added a score band checker, FICO range and program tables, Fannie Mae pricing bands and five new questions.